What commercial property appraisal covers
Commercial property appraisal applies the policy’s appraisal clause to a business, nonprofit or association claim. The panel is the same as on a homeowner claim, two appraisers and an umpire, but the scope is bigger and the paperwork is heavier. We represent strip-center owners in Billings, apartment owners in Missoula, condo associations in Bozeman and Big Sky, rural churches, and small manufacturers with steel buildings on the edge of town.
How it works for an owner or a board
- Authority. For an HOA or church, we confirm who can invoke appraisal and sign documents. Association bylaws and the master policy may both matter.
- Coverage map. We sort out which parts of the building fall under the master policy and which belong to unit owners or tenants. That boundary drives many condo disputes.
- Scope by system. We document roofing, envelope, interior finishes, mechanical and electrical separately, because each has its own pricing and depreciation.
- Pricing. Commercial labor and material costs vary a lot across Montana. A ski-town condo complex reached by a single road is priced differently from a warehouse on Interstate 90.
- Panel work. We negotiate the scope with the carrier’s appraiser and bring unresolved items to the umpire, item by item.
- Award. The award is usually broken out by building or coverage part so the owner, board or lender can follow it.
Common commercial disputes in Montana
Low-slope and metal roofs
Hail on a TPO or EPDM membrane can bruise the insulation board underneath without an obvious tear on top. On standing-seam or screw-down metal roofs, some policies limit or exclude purely cosmetic dents, so whether a dent affects function becomes the central question.
Multiple buildings, one claim
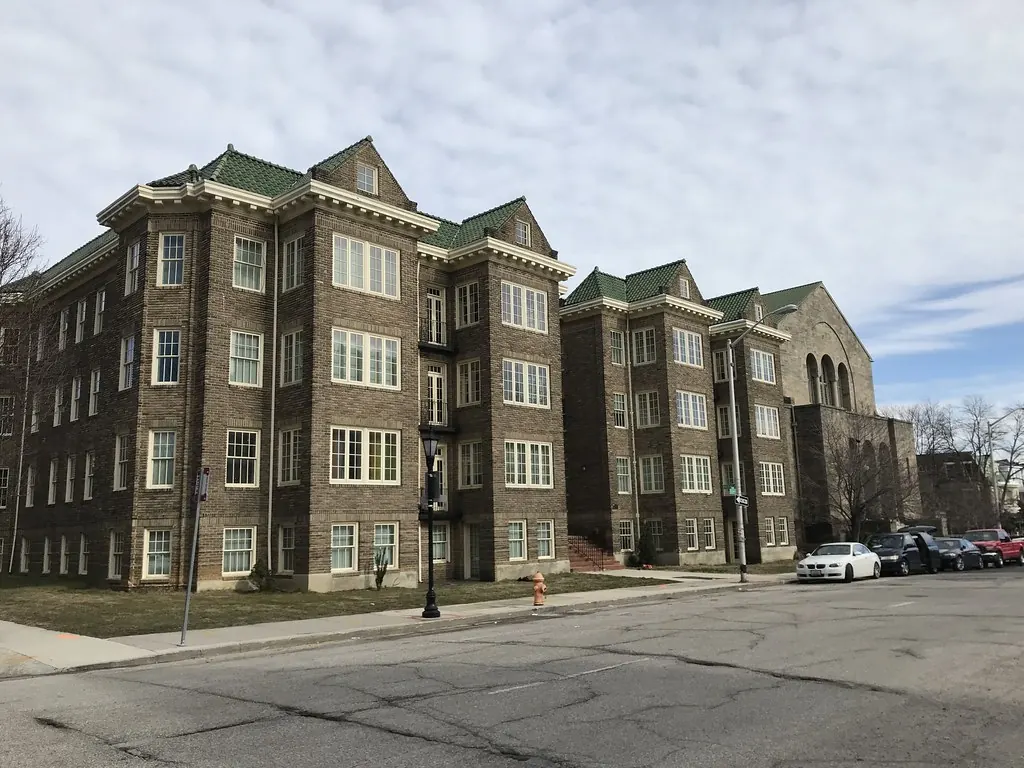
Apartment complexes and condo associations often have a dozen roofs with different ages. Carriers sometimes approve the worst few and patch the rest. Appraisal lets each building be decided on its own evidence.
Code and ordinance work
Larger repairs can trigger fire-separation, accessibility or energy code upgrades. Whether those costs are paid depends on the ordinance or law coverage in the policy and the limit attached to it.
Churches and older masonry
Brick and stone churches in towns like Lewistown or Miles City may need masons and stained-glass specialists who travel from out of the area. Those costs belong in the estimate.
Business income and extra expense claims can also be disputed, but they turn on financial records rather than construction cost. We handle the physical damage side and can coordinate with your accountant on the rest.
When commercial property appraisal is not the answer
If the insurer says the loss falls under an exclusion, that the damage predates the policy, or that a protective-safeguards condition was not met, those are coverage issues. An appraisal panel cannot resolve them. The same goes for disputes between an association and its unit owners over who is responsible for what. Boards facing those questions should talk with a licensed Montana attorney first.
Appraisal also may not fit a very large loss that is still developing, where the scope isn’t yet known. In that case an insurance estimate review can track the carrier’s numbers until the scope is stable.
Getting started
Send us the declarations page, the full policy, the carrier’s estimate and any contractor proposals. For hail-heavy markets, our Billings page and our hail and roof damage service explain what local commercial roof claims tend to involve. We will tell you plainly whether commercial property appraisal is likely to help.
Questions about commercial & hoa claims
Can a condo association invoke appraisal on its own?
Usually the named insured on the master policy, which is typically the association, can demand appraisal on the property that policy covers. The board generally needs to authorize it under the bylaws. Individual unit owners have their own policies for their interior and contents, and those claims are handled separately. Boards with questions about their authority should check with association counsel.
Do you handle claims on churches and nonprofits?
Yes. Churches, community halls and other nonprofit buildings carry commercial property policies with the same appraisal clauses. These buildings often have older masonry, tall roofs and specialty finishes like stained glass or pipe organs, so the scope needs care. We work with whoever the organization designates to make decisions and keep the board informed.
Can appraisal cover business income losses?
Some policies allow appraisal of business income or extra expense amounts, and some do not. Even where it is allowed, those numbers depend on financial records such as sales history and payroll rather than construction pricing. We focus on physical damage and can work alongside your accountant if the income portion is also in dispute.
How long does a commercial appraisal take?
It depends on the number of buildings, how far apart the two estimates are, and how quickly both appraisers can agree on an umpire. A single-building claim can move in weeks; a multi-building complex with dozens of disputed items takes longer. Building access, weather and the availability of specialty consultants all affect the timeline.