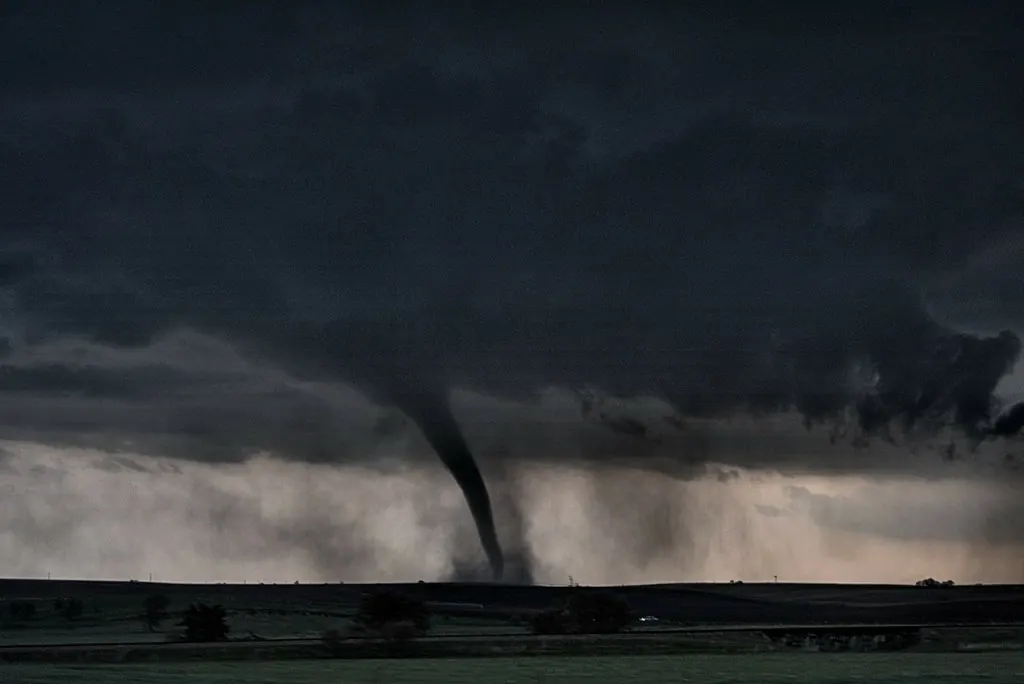
Montana wind is its own kind of peril
Wind damage in Montana comes in several forms. Downslope Chinook winds pour off the Rocky Mountain Front and through gaps like the one at Livingston, where strong gusts are routine for much of the year. Summer thunderstorms throw straight-line winds across the plains. Tornadoes happen too, mostly weak and mostly in eastern Montana, though the June 2010 tornado in Billings heavily damaged the MetraPark arena and nearby businesses. Each produces different damage patterns, and each can lead to a disputed claim.
How wind damage appraisal works
- Policy and deductible. We confirm the wind and hail deductible, any roof payment schedule, and the appraisal clause wording.
- Damage pattern. We document lifted and creased shingles, broken seal strips, missing ridge cap, loosened metal panels and fasteners, and siding that has been pulled or cracked.
- Repairability test. Creased or unsealed shingles may not reseal, especially on older roofs in cold climates. We note whether hand-sealing is realistic or whether the slope needs replacement.
- Interior follow-through. Wind-driven rain or snow through a breach can wet insulation, drywall and ceilings, sometimes weeks later.
- Estimate and panel. We price the work and present it to the carrier’s appraiser and, if needed, the umpire.
Disputes specific to wind claims
“Just a few shingles”
Carriers often approve replacing visibly missing shingles and nothing else. But wind can break the seal on many more shingles that still lie flat. A lifting test shows whether the rest of the slope is still holding. This is where wind damage appraisal earns its keep.
Metal roofing and screw-down panels
Rural homes, shops and barns often have exposed-fastener metal roofing. Repeated flexing in high wind can elongate screw holes and loosen panels. Repair scope should include refastening and, sometimes, panel replacement.
Tree and debris damage
In western Montana, wind brings down ponderosa and lodgepole pine onto roofs, decks and vehicles. Tree removal limits and whether the tree hit a covered structure both matter.
Siding and trim
Vinyl siding can crack in cold weather when wind slaps it against the wall. If the profile is discontinued, matching becomes the argument.
Wear versus wind
Carriers sometimes attribute damage to age rather than a wind event. Montana’s big temperature swings, intense high-altitude sun and repeated freeze-thaw cycles do age roofing faster, which makes the argument easy to raise and worth answering with evidence. Weather data, the pattern of damage and the timing of the claim all help sort that out.
If wind damage happened along the Front, near Livingston, Browning or Choteau, write down the date and save any weather alerts or news reports. Records of a specific gust event help connect the damage to a date of loss.
When appraisal won’t help
If the carrier denies the claim on the grounds that the damage is wear and tear, a manufacturing defect or poor installation, that is a coverage dispute. Appraisal panels generally decide amount, and how far they can go on causation varies by policy wording. Talk to a licensed Montana attorney about a denial. Appraisal is also a poor fit when the main issue is the deductible itself rather than the repair cost.
Related help
Wind and hail often arrive in the same storm, so our hail and roof damage page may also apply. For local context, see our Livingston page. To see what you net after a percentage deductible, try the wind and hail deductible calculator. If you think wind damage appraisal fits your claim, send us your estimate.
Questions about wind & tornado damage
Do Montana policies have separate wind deductibles?
Many do. Some policies have a separate wind and hail deductible, which may be a flat amount or a percentage of the dwelling limit. A percentage deductible can be much larger than the standard one. Check your declarations page, and keep in mind that the appraisal award sets the loss amount before the deductible is subtracted.
Can appraisal decide whether wind caused the damage?
That depends on your policy wording and how the dispute is framed. Appraisal is mainly about the amount of loss. Some panels consider which damage was caused by the storm as part of measuring the loss, but a flat denial based on wear or an exclusion is a coverage question. A licensed Montana attorney can explain how that applies to your situation.
A tree fell on my house in a windstorm. Is that an appraisal case?
If the carrier accepts the claim but you disagree about the cost of repairs, removal or cleanup, appraisal can resolve the amount. Many policies limit what they pay for tree removal and debris, and those limits still apply. If the carrier is disputing whether the tree damage is covered at all, that is a coverage issue rather than an amount issue.